retirement savings by age
Retirement Savings by Age: Benchmarks and Catch-Up Moves
Learn retirement savings by age benchmarks, how to estimate progress, understand common savings formulas, and explore practical catch-up moves with clear examples.
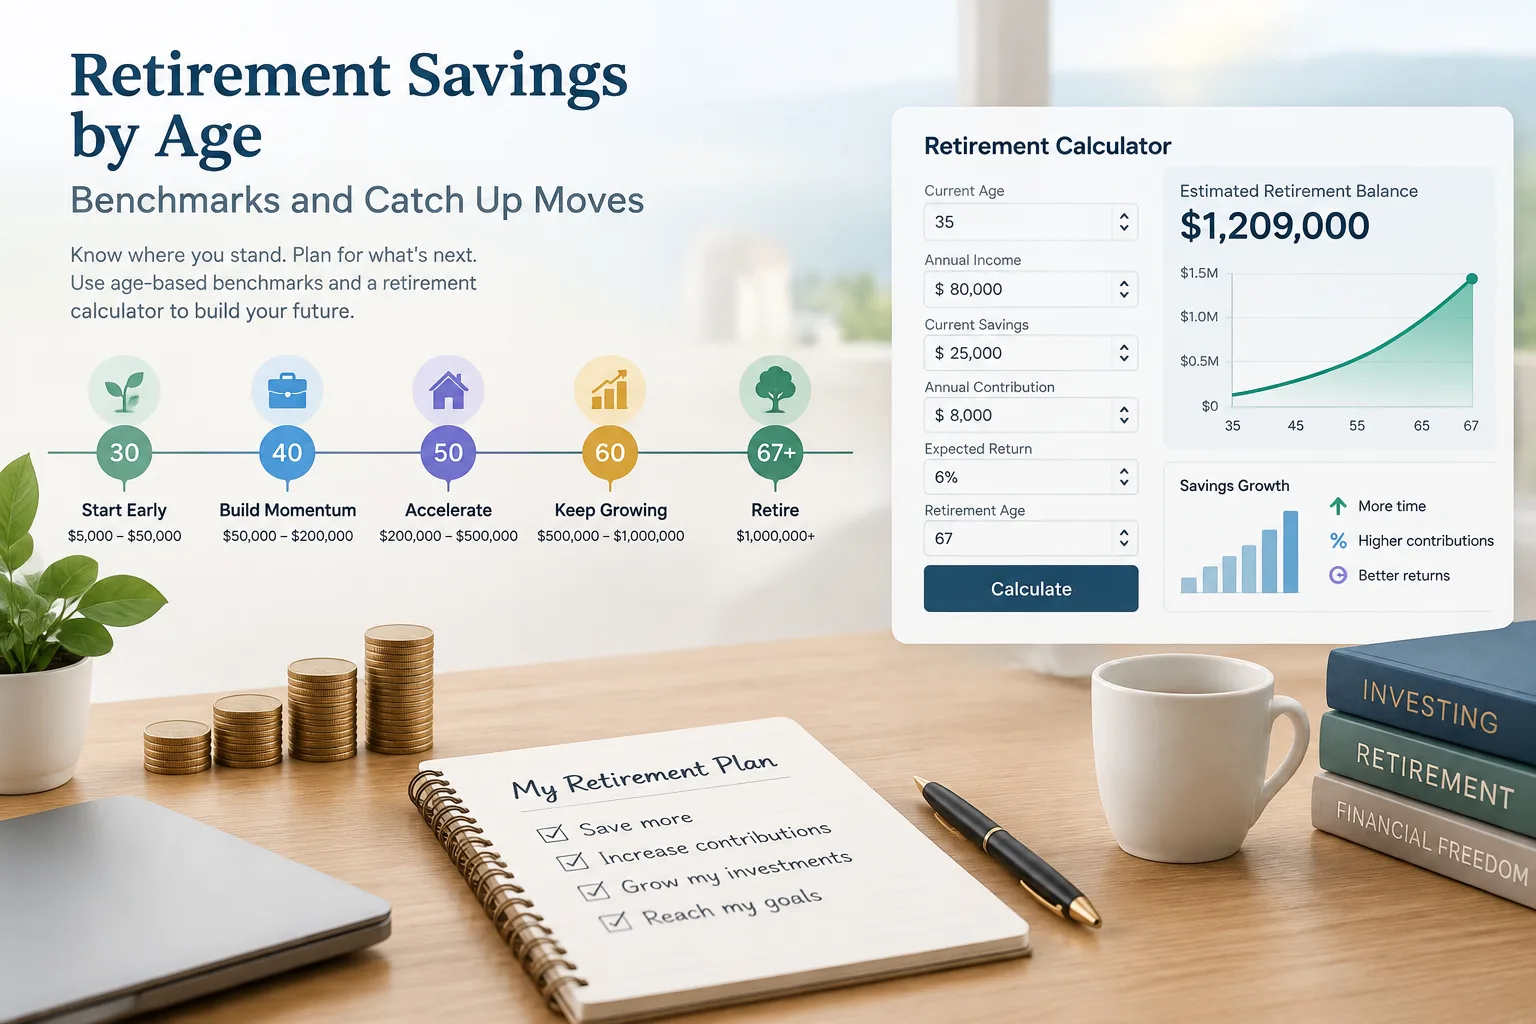
Retirement savings by age are reference points that help people estimate whether their current savings level is broadly aligned with their retirement goals. These benchmarks compare your accumulated retirement assets with factors such as age, income, time horizon, and savings habits. They are useful for employees, self-employed workers, and anyone reviewing long-term financial progress. Use a retirement calculator to estimate future balances based on your own assumptions rather than relying only on general benchmarks.
What Does Retirement Savings by Age Mean?
Retirement savings by age refers to common savings milestones that show how much money someone may have accumulated at different stages of life. These milestones are not rules or guarantees. They are simple reference points designed to help people evaluate their current position and identify whether adjustments may be needed.
A retirement savings benchmark often considers:
- Current age
- Annual income
- Retirement age goal
- Expected retirement lifestyle
- Contribution rate
- Employer retirement benefits
- Investment time horizon
For example, someone in their 30s may have fewer saved dollars than someone in their 50s but still be progressing well if they are consistently contributing and have many years before retirement.
A retirement savings by age chart is usually a comparison tool, not a prediction. Different households have different expenses, responsibilities, and financial goals, so personal calculations are more useful than comparing against a single average number.
Common Retirement Savings Benchmarks by Age
Many financial discussions use income multiples as simple retirement savings benchmarks. A common approach is to compare retirement savings with annual income.
Example benchmark ranges may look like this:
| Age range | Example savings benchmark |
|---|---|
| 30s | Around 1x annual income as a reference point |
| 40s | Around 3x annual income as a reference point |
| 50s | Around 6x annual income as a reference point |
| 60s | Higher multiples depending on retirement timing and goals |
These examples are only educational reference points. Actual needs can vary significantly depending on expected spending, healthcare costs, housing situation, pension income, and other financial resources.
How Retirement Savings Are Calculated
A basic retirement savings estimate usually combines current savings, future contributions, and potential account growth.
A simplified future value formula is:
Where:
- (FV) = estimated future retirement balance
- (P) = current retirement savings balance
- (r) = annual growth rate expressed as a decimal
- (t) = number of years invested
- (C) = annual contribution amount
This formula assumes a constant annual growth rate and regular contributions. Real account values can change because actual returns vary over time.
Retirement Savings Example Calculation
Suppose a person has:
- Current retirement savings: $20,000
- Annual contribution: $5,000
- Time until retirement: 20 years
- Assumed annual growth rate: 5% (0.05)
First, calculate growth of current savings:
The estimated value is about $53,066.
Next, calculate the future value of annual contributions:
The estimated value is about $165,330.
Combined estimate:
Under these assumptions, the estimated retirement balance would be about $218,396. This is a mathematical projection, not a guaranteed outcome.
How to Use Retirement Savings by Age Benchmarks
Step 1: Check Your Current Retirement Savings
List your current retirement accounts and balances. Include relevant accounts such as employer plans or individual retirement accounts where applicable.
Step 2: Compare With an Age-Based Reference Point
Compare your savings amount with general retirement savings by age benchmarks. Consider your income level and retirement timeline instead of looking only at age.
Step 3: Estimate Future Growth
Use a retirement calculator to test different contribution amounts, time periods, and growth assumptions. You can also compare scenarios using tools such as a compound interest calculator.
Step 4: Review Your Savings Rate
If your projected savings appear lower than your goal, possible adjustments may include increasing contributions, extending the savings period, or reviewing expected retirement expenses.
Step 5: Update Your Estimate Regularly
Retirement planning changes over time. Review your assumptions when your income, expenses, retirement plans, or financial priorities change.
Catch-Up Moves If Your Retirement Savings Are Behind
Being below a benchmark does not automatically determine your retirement outcome. Several practical steps may help improve your future estimate:
Increase Regular Contributions
Increasing consistent contributions can have a meaningful impact because additional savings have more time to potentially grow.
Review Your Retirement Timeline
Some people adjust their retirement timing based on savings progress, expenses, or personal goals. A longer saving period can change the calculation results.
Reduce Unnecessary Future Expenses
Estimating future spending can help clarify how much retirement savings may be needed. Lower expected expenses can change the amount required for retirement.
Consider Employer Retirement Benefits
Employer contributions or retirement benefits may affect the total resources available during retirement. Include them when building a complete estimate.
Common Mistakes and Limits of Retirement Savings Benchmarks
Treating Benchmarks as Exact Targets
Age-based charts are general references. They do not account for every person's income, expenses, family situation, or retirement goals.
Ignoring Inflation
Future expenses may be higher than current expenses because prices can change over time. Retirement estimates should consider purchasing power.
Assuming a Fixed Investment Return
Calculation examples often use a constant growth rate for simplicity. Actual returns may be higher or lower and can vary from year to year.
Comparing Without Considering Income
A savings amount means different things for different incomes. A person with a higher income may need a different savings target than someone with a lower income.
Who Should Use Retirement Savings by Age Calculations?
These calculations can help:
- Workers checking long-term savings progress
- People preparing for retirement decisions
- Individuals reviewing contribution levels
- Households estimating future financial needs
Calculator Lists provides free online financial calculators that help users explore different scenarios with transparent formulas. Try the retirement calculator to estimate possible future savings outcomes based on your own inputs.
FAQ: Retirement Savings by Age
How much should I have saved for retirement by my age?
There is no single required amount because retirement needs depend on income, expenses, retirement age, and personal goals. Age-based benchmarks can provide a general comparison, but a personalized calculation is usually more useful.
What is a good retirement savings goal in your 30s?
A common benchmark discussion suggests having savings equal to roughly one year of income by age 30 as a reference point. However, actual needs depend on savings habits, income changes, and retirement plans.
How can I calculate if my retirement savings are on track?
You can estimate progress by comparing your current savings, future contributions, expected retirement date, and assumed growth rate. A retirement calculator can help organize these inputs.
Can I catch up if I started saving late?
Yes, people who start later may explore options such as increasing contributions, adjusting retirement timing, or reviewing expected expenses. The impact depends on individual circumstances.
Are retirement savings benchmarks guaranteed?
No. Benchmarks are educational guidelines only. They do not guarantee a specific retirement outcome and should not replace personal financial planning.
Looking for more tools?
Try our free Free Calculators