mortgage
How Does Mortgage Interest Work?
Learn how mortgage interest works, how it is calculated, how amortization changes your payments, and how to estimate costs with a mortgage calculator.
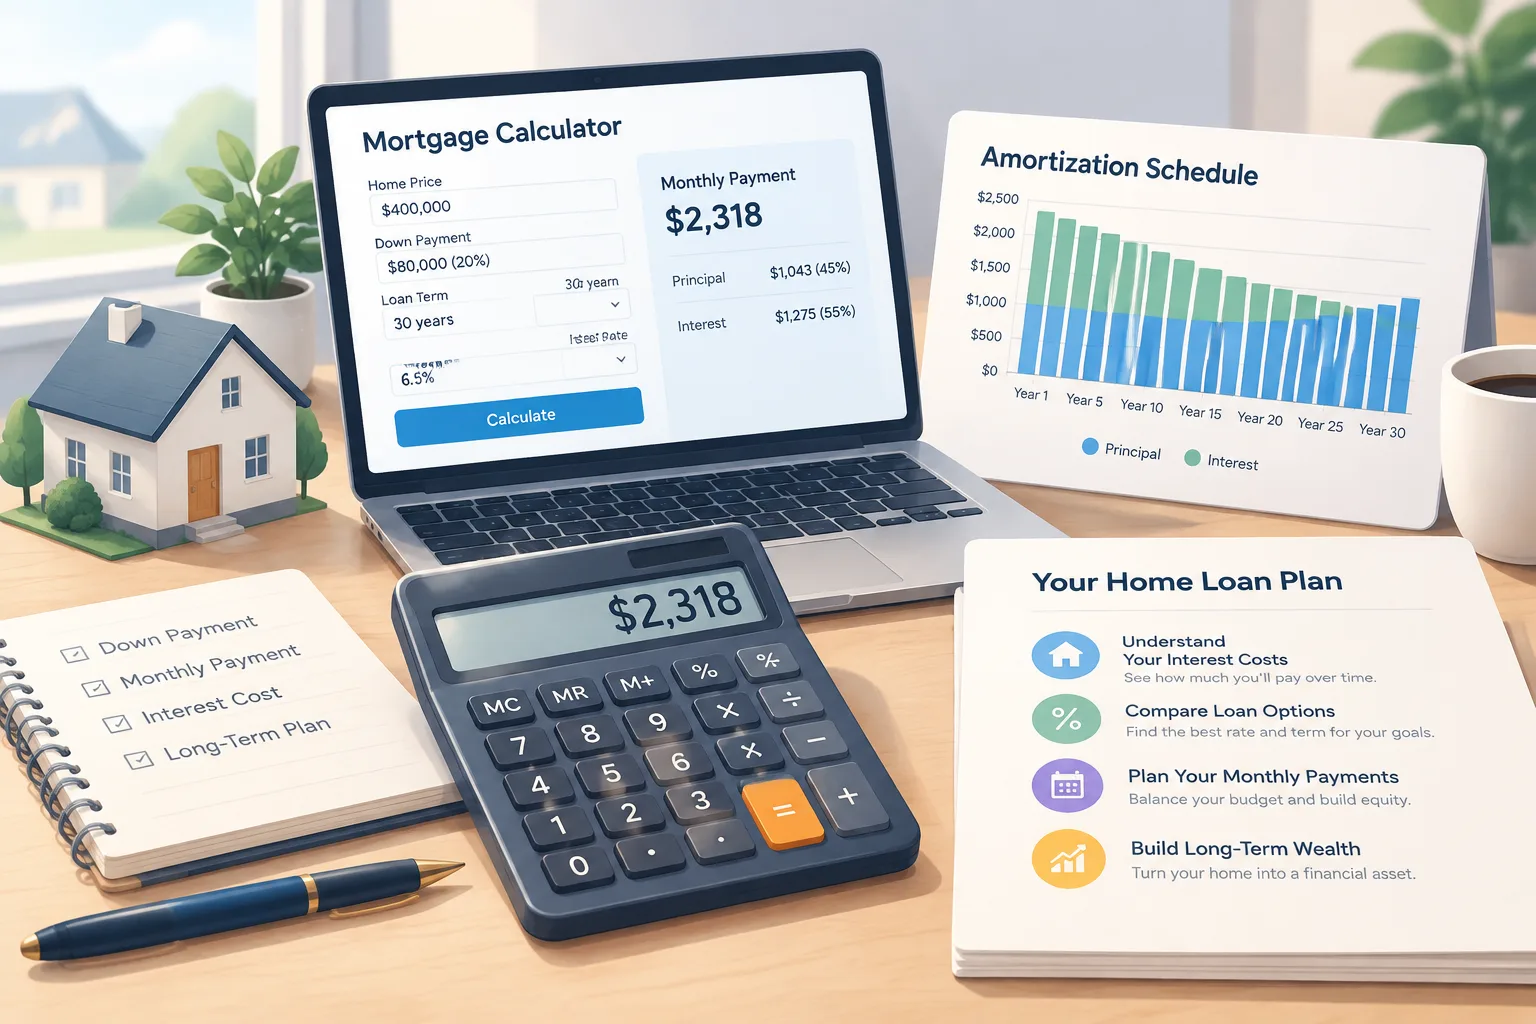
Mortgage interest is the cost charged by a lender for borrowing money to buy a home. It is calculated based on the loan balance, interest rate, and repayment schedule. Home buyers, homeowners comparing loans, and anyone reviewing monthly payments can use a mortgage calculator to estimate interest costs and understand how payments are divided between principal and interest.
What Is Mortgage Interest?
A mortgage is a loan used to purchase real estate, and interest is the amount paid to the lender for providing access to borrowed funds. When you make a mortgage payment, part of the payment usually reduces the loan balance, while another part covers interest charges.
The amount of interest you pay changes over time because mortgage loans are usually amortized. At the beginning of the loan, the balance is larger, so the interest portion of each payment is often higher. As you repay the loan, the balance decreases, and more of each payment may go toward reducing principal.
Mortgage interest depends on several factors:
- Loan amount: The original amount borrowed from the lender.
- Interest rate: The percentage charged annually on the outstanding balance.
- Loan term: The length of time used to repay the loan.
- Payment frequency: How often payments are made.
- Loan structure: Fixed-rate and adjustable-rate mortgages may calculate interest differently over time.
A mortgage calculator can help estimate monthly payments and total interest costs, but the results depend on the assumptions entered. Actual loan terms may include additional costs such as taxes, insurance, fees, or lender-specific charges.
How Mortgage Interest Is Calculated
For many fixed-rate mortgages, interest is calculated using the loan balance and the periodic interest rate. A common monthly interest calculation is:
Where:
- (I) = interest charged for the payment period
- (B) = current loan balance
- (r_m) = monthly interest rate
The monthly interest rate is calculated by dividing the annual interest rate by the number of payment periods per year:
Where:
- (r) = annual interest rate as a decimal
- 12 = number of monthly payment periods in a year
Mortgage Payment Formula
A common fixed-rate mortgage payment formula is:
Where:
- (M) = monthly mortgage payment
- (P) = loan principal
- (r_m) = monthly interest rate
- (n) = total number of monthly payments
This formula calculates the scheduled principal and interest payment. It does not automatically include costs such as property taxes, homeowners insurance, or other expenses unless they are added separately.
Example Calculation
Suppose a borrower has:
- Loan amount: 300,000 dollars
- Annual interest rate: 6 percent
- Loan term: 30 years
First convert the annual rate into a monthly rate:
The total number of payments is:
Substituting these values into the mortgage payment formula gives an estimated monthly principal and interest payment of about 1,799 dollars.
The first month's interest portion can be estimated as:
So the first payment may include about 1,500 dollars of interest and about 299 dollars reducing the principal. Over time, the interest portion decreases as the remaining balance becomes smaller.
You can use the mortgage calculator to test different loan amounts, rates, and terms.
How Amortization Changes Mortgage Interest Over Time
Amortization is the process of gradually paying off a loan through scheduled payments. Each payment is divided into interest and principal portions.
At the start of a mortgage:
- The loan balance is at its highest.
- Interest charges are larger because they are based on a larger balance.
- A smaller portion of the payment reduces principal.
Later in the mortgage:
- The remaining balance becomes smaller.
- Interest charges decrease.
- More of the payment goes toward principal reduction.
An amortization schedule shows this change payment by payment. Reviewing an amortization table can help borrowers understand how extra payments, refinancing, or different loan terms may affect total interest costs.
For a detailed payment breakdown, the amortization calculator can help visualize how a loan balance changes over time.
How to Calculate Total Mortgage Interest
Total mortgage interest is the difference between the total amount paid and the original loan amount.
The basic calculation is:
Where:
- (M) = monthly payment
- (n) = number of payments
- (P) = original loan principal
Example:
If a mortgage payment is 1,799 dollars for 360 months:
Then:
This simplified example shows that the total interest paid can be a significant part of the overall borrowing cost. Actual results may differ because of changing rates, fees, additional payments, or other loan terms.
Steps to Estimate Mortgage Interest Costs
1. Enter the Loan Information
Start with the main details:
- Purchase price or loan amount
- Down payment amount if applicable
- Interest rate
- Loan term
A larger down payment generally reduces the amount borrowed, which can reduce the interest calculated on the loan balance.
2. Choose the Payment Schedule
Most mortgage examples use monthly payments, but some loans may have different schedules. The payment frequency affects how interest is calculated.
3. Review Monthly Payment Results
A mortgage calculator can show the estimated principal and interest payment. This helps compare different loan scenarios without manually repeating calculations.
4. Check Total Interest Over the Loan Term
Monthly affordability is only one part of mortgage planning. Looking at total interest can provide a clearer view of the long-term borrowing cost.
5. Compare Different Scenarios
Try adjusting one factor at a time, such as:
- Shorter versus longer loan terms
- Higher versus lower interest rates
- Different loan amounts
This can help explain how each factor changes the calculation.
Common Mortgage Interest Mistakes and Limitations
Confusing Interest Rate With Total Loan Cost
The interest rate is only one part of borrowing costs. A loan may also involve fees, insurance, taxes, and other expenses. A mortgage calculator estimate should be viewed as a planning tool, not a final loan offer.
Assuming Monthly Payments Stay the Same for Every Mortgage
Fixed-rate mortgages usually have predictable principal and interest payments, but adjustable-rate mortgages may change when the interest rate changes.
Ignoring the Effect of Loan Term
A longer loan term often lowers the monthly payment but may increase total interest paid over time. A shorter term may reduce total interest but require higher monthly payments.
Using Incorrect Inputs
Small changes in the loan amount, rate, or term can affect results. Always check that the numbers entered match the scenario being evaluated.
Treating Calculator Results as Financial Advice
Mortgage calculators provide estimates based on entered information. They do not replace professional financial guidance or lender disclosures.
FAQ About Mortgage Interest
How does mortgage interest work each month?
Mortgage interest is usually calculated from the remaining loan balance and the periodic interest rate. Early payments often contain more interest because the balance is higher. As the balance decreases, the interest portion generally becomes smaller.
Is mortgage interest calculated daily or monthly?
The calculation method depends on the mortgage agreement and lender practices. Many examples use monthly calculations, but some loans may use daily interest calculations. Review the loan terms for the exact method.
Why do I pay more interest at the beginning of a mortgage?
Early in the loan, the outstanding balance is larger. Since interest is based on the remaining balance, the interest portion is typically higher during the first years of repayment.
How can I estimate my total mortgage interest?
You can estimate total interest by calculating the total of all scheduled payments and subtracting the original loan amount. A mortgage calculator can perform this calculation automatically using your loan details.
Does paying extra reduce mortgage interest?
Additional payments that reduce the principal balance may lower future interest charges because interest is calculated on a smaller balance. The effect depends on the mortgage terms and payment rules.
Use a Mortgage Calculator to Explore Different Scenarios
Understanding how mortgage interest works makes it easier to compare loan options and interpret payment estimates. Use the mortgage calculator to explore how loan amount, interest rate, and repayment period can affect estimated payments and interest costs.
Looking for more tools?
Try our free Free Calculators